NZ Seize the Day: Lessons from New Zealand's Refrigerant Management for Australia.
Mansfield Advisory Pty Ltd
200 followers
February 5, 2025
Following our previous article on illicit refrigerant trade (here), it's worthwhile seeing what is happening across the ditch and learn from how New Zealand is actively shaping its regulatory landscape to meet global environmental goals and their successes in seizure of Illegal HFCs.
New Zealand's Approach to Refrigerants
New Zealand has been proactive in implementing the Kigali Amendment to the Montreal Protocol, which aims to phase down the use of hydrofluorocarbons (HFCs), potent greenhouse gases. The country has introduced strict controls on the import, use, and disposal of refrigerants, emphasizing the need for sustainable practices and the transition to lower-GWP (Global Warming Potential) alternatives. This includes:
- Mandatory Reporting: Businesses handling refrigerants must report their usage and emissions to ensure compliance with national and international commitments.
- Training and Certification: There is a strong focus on training technicians to handle refrigerants safely and efficiently, reducing leaks and emissions.
- Recovery and Recycling: Encouraging the recovery, recycling, and proper disposal of refrigerants to prevent environmental harm.
Since 2013, New Zealand's Emissions Trading System (ETS) has been crucial in managing refrigerants by including HFCs in its regulatory framework. The ETS imposes import taxes on new refrigerants based on their Global Warming Potential (GWP) and products containing HFCs, such as motor vehicles and pre-charged equipment. For 2024, the carbon price is set at NZD $71.97 per metric ton of CO2e, incentivizing the destruction of HFCs by allowing regulated entities to earn New Zealand Emissions Units (NZUs) for each tonne of CO2 equivalent destroyed.
The future effect on the atmosphere (measured by carbon dioxide (CO2) equivalent) of new bulk HFCs imported into New Zealand will be reduced gradually until 2036 (see graph below).
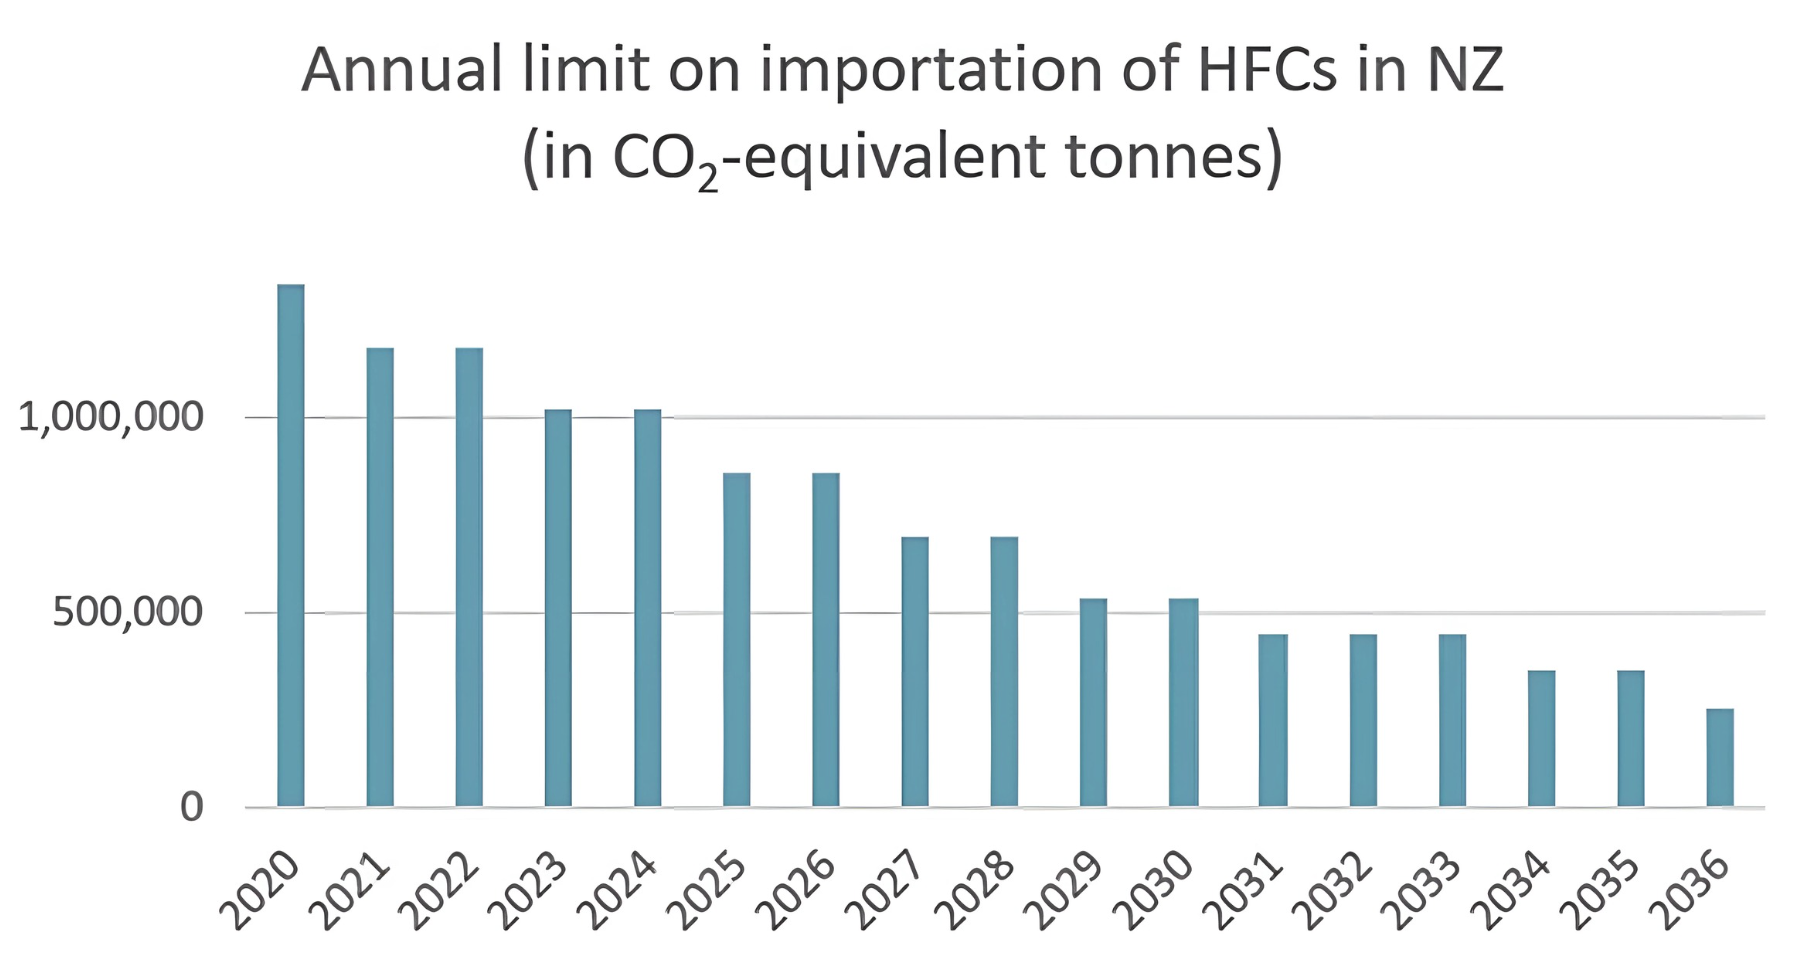
Graph showing annual limit on importation of HFCs into New Zealand 2020-2036 (in CO2-equivalent tonnes)
Product Stewardship on Synthetic Refrigerants in New Zealand
The New Zealand Government has recently approved regulations to establish Cool-Safe as the official Product Stewardship Organisation for Synthetic Refrigerants, managed by the Trust for the Destruction of Synthetic Refrigerants. Once enacted, all synthetic refrigerants and related equipment must comply with this scheme, which requires:
- Data Reporting: The refrigerant sector must report usage data to Cool-Safe for lifecycle tracking.
- Training Standards: Effective three years after regulation, sales and recovery of refrigerants and equipment will be restricted to those with industry-recognized training.
Cool-Safe has traditionally handled voluntary recovery and destruction of HFCs and ODS, funded by a levy on bulk HFC imports and NZU sales from their activities. From 2024, participation becomes mandatory, offering incentives at NZD $25 per kg for recovered refrigerant, with increased rates for volumes over 500 kg. This shift, along with the 2023 policy allowing any ETS-regulated entity to generate NZUs from HFC destruction, highlights New Zealand's commitment to greenhouse gas reduction.
For more details:
- Read about the Synthetic Refrigerant Stewardship here
- Check out the Cool-Safe website.
Recent Seizure of Illegal HFCs
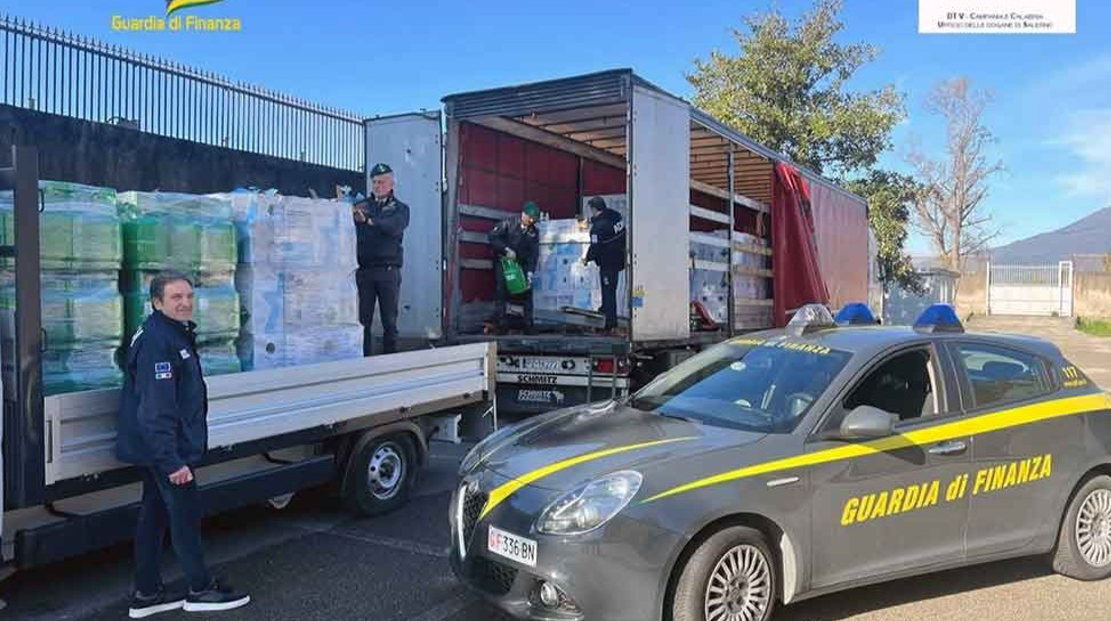
In a significant move to enforce these regulations, the Environmental Protection Authority (EPA) of New Zealand recently conducted an investigation leading to the seizure of HFC gases. This operation highlights the government's vigilance against illegal imports that could undermine the environmental efforts to reduce HFC emissions. The EPA's actions underscore the seriousness with which New Zealand treats its international environmental obligations and domestic laws regarding refrigerant management. This seizure, amounting to 3 tonnes of HFCs, could have a significant environmental impact. Assuming a mix of common HFCs:
- If we consider the HFCs primarily HFC-134a (GWP 1,430), this seizure would be equivalent to approximately 4,290 tonnes of CO2.
- However, if the HFCs were more like HFC-404A (GWP 3,922), the impact would be approximately 11,766 tonnes of CO2 equivalent.
Therefore, depending on the composition of the HFCs involved, this seizure could have an environmental impact of 4,290 to 11,766 tonnes of CO2 equivalent. This range illustrates the potential magnitude of greenhouse gas emissions this enforcement action prevents. This seizure signifies a commitment to environmental stewardship and serves as a warning to those who might consider circumventing the strict regulations for the importation and use of HFCs.
Relevance to Australia
The actions taken by New Zealand are particularly relevant for Australia, as both countries share similar environmental challenges and are part of the same regional ecosystem. Australia, like New Zealand, is a signatory to the Kigali Amendment and is in the process of adapting its regulations concerning refrigerants:
- Regulatory Alignment: Australia can learn from New Zealand's proactive approach to enforcing and monitoring refrigerant use.
- Cross-Border Implications: The illegal trade of refrigerants could easily spill over from one country to another, affecting both nations' efforts to reduce greenhouse gas emissions.
- Innovation and Collaboration: There's an opportunity for both countries to collaborate on technology and policy innovations that could lead to more effective refrigerant management.
Comparison with New Zealand's Approach:
While Refrigerant Reclaim Australia (RRA) operates a stewardship program, it differs from the newly proposed Cool-Safe initiative in New Zealand. RRA focuses more on the end-of-life phase of refrigerants within a co-regulatory framework that involves industry self-regulation. In contrast, New Zealand's scheme aims for a holistic lifecycle management approach backed by new regulations to enforce compliance. Australia could expand RRA's role or develop a new framework (and oversight entity) to align more closely with this comprehensive lifecycle stewardship model, enhancing environmental and regulatory outcomes. Key aspects:
- Mandatory Lifecycle Tracking: NZ's Cool-Safe scheme will require lifecycle tracking from sale to recovery, offering a more comprehensive approach than RRA's current focus solely on end-of-life management.
- Training Mandates: NZ plans to introduce mandatory training for those handling refrigerants, contrasting with Australia, where such training, while encouraged, is not explicitly mandated under RRA's stewardship but managed through other industry bodies and legislative requirements.
- Broader Scope: The proposed NZ scheme encompasses new sales and end-of-life management, potentially involving a wider range of stakeholders in the lifecycle process than RRA's current model.
- Legal Framework: NZ's approach involves crafting new regulations specifically for stewardship, whereas Australia's integrates refrigerant management into existing environmental protection laws.
Australian Stewardship Considerations:
- Mirror NZ's Scheme: Australia could consider establishing a similar product stewardship scheme for refrigerants, leveraging existing bodies like RRA or a new trust similar to New Zealand's Trust for the Destruction of Synthetic Refrigerants to manage it.
- Legislative Action: Push for legislation akin to NZ's, mandating refrigerant lifecycle tracking, reporting, and training standards to ensure safe handling and disposal.
- Enforcement and Collaboration: Strengthen cross-border cooperation with New Zealand to combat illegal refrigerant trade, enhancing enforcement mechanisms based on New Zealand's success.
- Public and Industry Education: Similar to NZ's approach, initiate campaigns to educate the public about the benefits of stewardship and encourage compliance and innovation in refrigerant management.
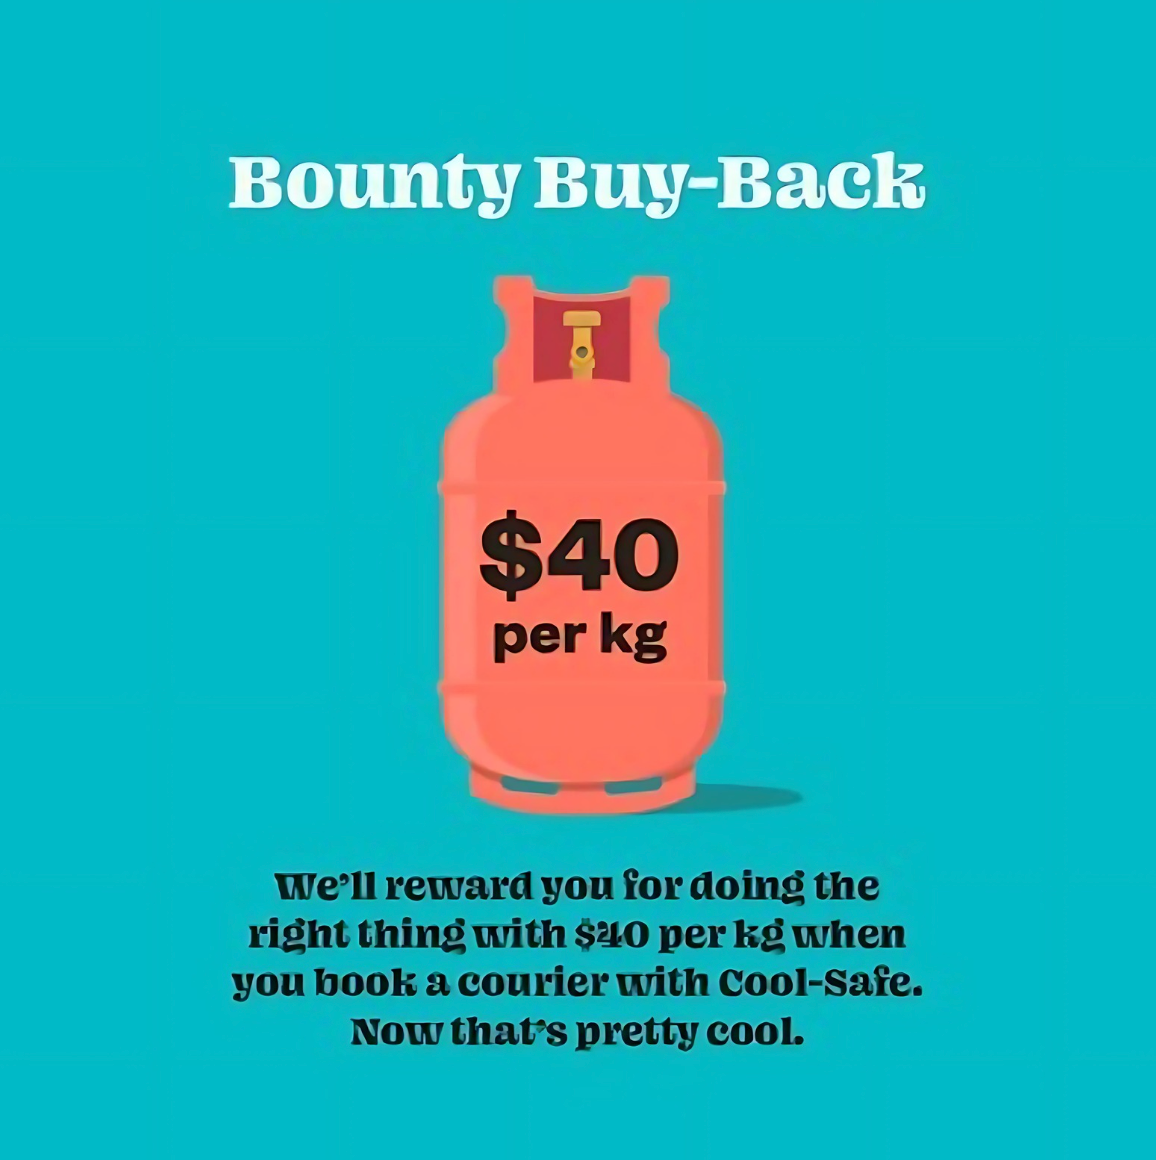
Cool Safe NZ
Valuing Refrigerant Recovery: New Zealand vs. Australia
New Zealand has taken an innovative approach to encouraging refrigerant recovery with its Cool-Safe Buy-Back programmes. Initiated in October 2022, these programmes reward companies and technicians for responsibly managing synthetic refrigerants, promoting a culture of environmental responsibility:
- Bounty Buy-Back Programme: In May 2024, the payment for recovered refrigerants was increased to $40 per kilogram, a significant jump from $25. This increase is influenced by New Zealand's Emissions Trading Scheme (ETS), where the carbon price for 2024 is set at NZD $71.97 per metric ton CO2e. This incentive covers the costs of recovery and financially benefits those who participate by aligning with the environmental cost of HFC emissions.
- Bulk Refrigerant Buy-Back: Even higher rates are offered for 200 kilograms or more recoveries, ensuring that bulk handlers are also motivated to participate in the programme. This structure reflects the economic benefits of reducing large quantities of HFCs under the ETS framework.
In stark contrast, Australia has adopted a different strategy for its refrigerant management:
- Fixed Levy: Australia maintains a fixed levy of AUD $2.00 (NZD $2.21 as of 5th Feb 2025) per kilogram for refrigerant recovery. The Australian Competition and Consumer Commission (ACCC) re-authorised this arrangement in 2021, locking it in for ten years. Refrigerant Reclaim Australia (RRA) indicated they “saw no need to increase this levy over the next ten years.” Unlike New Zealand, Australia's levy does not factor in carbon pricing and lacks the integration of an ETS or similar mechanism for refrigerants.
This fundamental difference in approach highlights two key points:
- Economic Incentive: New Zealand's system directly incentivises refrigerant recovery and proper disposal by providing a financial benefit that grows with the volume and urgency of the environmental need. In contrast, Australia's static levy, which does not include carbon pricing, might not adequately reflect the increasing value of responsible refrigerant management in the fight against climate change.
- Long-term Commitment: Australia's decision to lock in the low levy rate for ten years could hinder the country's adaptability to changing environmental priorities and economic conditions. Meanwhile, New Zealand's dynamic pricing model, influenced by its ETS, allows for adjustments to encourage more participation as the environmental stakes rise, making it more responsive to the need to reduce greenhouse gas emissions.
This comparison underscores the potential for Australia to reconsider its strategy in light of New Zealand's success in engaging its industry with economic incentives for sustainability (and having a carbon price mechanism factored in), potentially leading to more effective refrigerant management and more significant environmental benefits.
Why This Matters:
- Environmental Impact: Reducing HFCs is crucial for combating climate change due to their high global warming potential.
- Compliance with International Agreements: Demonstrates New Zealand's leadership in adhering to global environmental agreements like the Kigali Amendment, setting a precedent for Australia.
- Economic Implications: This policy encourages innovation in refrigerant technology and supports the growth of industries focused on sustainable solutions, which could also benefit Australia economically.
The seizure development in New Zealand (article here) also reminds Australian businesses and policymakers to remain vigilant and proactive in their approach to environmental compliance and sustainability. The EPA's investigation involved several search warrants executed across New Zealand. So far, 3 tonnes of HFCs have been seized, and the investigation is ongoing. Offences can result in a fine and, in some cases, up to five years’ imprisonment.
Capitalizing on the Transition to Sustainable Cooling:
Australia is at a defining moment where its approach to refrigerant regulation could lead the way in global sustainability efforts. Businesses are now tasked with navigating the complexities of mandatory emissions disclosure while being acutely aware of the burgeoning issue of illegal refrigerant trade, as highlighted in our previous discussion on illicit refrigerants (see previous post here).
Australian companies can manage risks and seize opportunities within the emerging low-carbon economy by vigilantly monitoring refrigerant use, adopting appropriate lower GWP alternatives, and strengthening compliance mechanisms. New Zealand's proactive measures, such as the recent seizure of illegal HFCs, serve as a clear example of the enforcement needed to combat the illicit trade that undermines environmental efforts.
Alignment with international best practices does more than ensure regulatory compliance; it elevates Australian businesses to the forefront of the worldwide movement towards responsible cooling solutions. This pivotal moment demands collaboration among government bodies, industries, and innovators to tackle refrigerant smuggling, slash emissions, and spearhead technological advancements.
By adapting proactively to these changes, Australia will not only significantly lower its carbon footprint and address legacy issues but also enhance its standing in the global effort against climate change, promoting economic fortitude and ecological stewardship.
What steps should Australian businesses take to mirror New Zealand's success in managing refrigerants?"
#Refrigerants #KigaliAgreement #Cooling #PFAS #SustainableCooling #ClimateAction
Notes
- NZ EPA encourages anyone being offered bottles of HFCs at significantly lower than market price to contact our investigations team in confidence at investigations@epa.govt.nz
- Anyone importing bulk HFCs needs a permit under the Ozone Layer Protection Act and must be registered as a participant in the Emissions Trading Scheme. Bulk HFCs are containers of new or recycled HFC gas in an unprocessed form, alone or in a mixture.
- Permits are not needed to import HFCs into goods, such as car air conditioning or fire extinguishers. However, under the CCRA, goods containing synthetic greenhouse gases, including HFCs, are subject to a levy.
References:
EPA Seizes HFC gases in illegal import investigation https://www.epa.govt.nz/news-and-alerts/latest-news/epa-seizes-hfc-gases-in-illegal-import-investigation
NZ Rules for HFCs https://www.epa.govt.nz/hazardous-substances/certificates-permits-and-permissions/hydrofluorocarbon-gases-hfcs-import-and-export/the-rules-for-hfcs/
ACCC Ruling on Application for revocation of A91515 and the substitution of authorisation AA1000537 lodged by Refrigerant Reclaim Australia Limited in respect of its operation of a product stewardship program to recover ozone-depleting and synthetic greenhouse gas refrigerants (May 2021). https://www.accc.gov.au/system/files/public-registers/documents/Final%20Determination%20-%2012.05.21%20-%20PR%20-%20AA1000537%20-%20RRA.pdf
First published on LinkedIn 5th February 2025